Noticias del mercado
-
20:05
US dollar back on top for start of the week, 105.50 eyed
- US dollar bulls are moving back in and eye 105.50s.
- The market's sentiment is fickle which plays into the hands of the greenback.
- US data will be critical this week with NFPs and Fed minutes eyed.
The US dollar was in demand at the start of the new month and quarter for its safe-haven status, dragging a number of rivals back down to earth. The euro fell to a low of 1.0365 vs the greenback from a high close to the 1.05 area and the Aussie sank to fresh cycle bear lows at 0.6763.
Tighter monetary expectations in the face of higher in inflation are feeding a bid into the greenback due to the demand for US assets which has sent the benchmark 10-year US Treasury yields to one-month lows. The US 10-year yield dropped 8.5 basis points to 2.89%.
Nevertheless, US equity benchmarks were higher in the first session of the third quarter, recouping some of the ground lost in Thursday's session finished up the worst first half-seen in decades. The Dow Jones Industrial Average added 1.1% to 31,097.26, the S&P 500 was also up by 1.1% to 3,825.33, and the Nasdaq Composite was around 1% higher at 11,127.85. For the week, the Dow was 1.3% lower, the S&P 500 dropped 2.2%, and the Nasdaq fell 4%.
in data, which hampered down the risks of recession sentiment in global markets showed that the Institute for Supply Management's US manufacturing index fell to 53 from 56.1 in May, compared with expectations of 54.5. This was the weakest since June 2020, when the world was in the throes of the COVID-19 pandemic.
As a consequence, a flight to safety sent the US 10-year yield dropped 6.8 basis points to 2.91% as traders await the outcome of this week's minutes of the Federal Reserve's June meeting when it raised interest rates by 75 basis points. This was the most in almost three decades, amid concern that further projected rate hikes in the Fed pipeline are likely to tip the economy into a recession.
For the week ahead, Nonfarm Payrolls will be key and the data is expected to show that Employment likely continued to advance firmly in June but at a more moderate pace after three consecutive job gains of around 400k in March-May, the analysts at TD Securities said. ''High-frequency data, including Homebase, still point to above-trend job creation. We also look for the UE rate to stay unchanged at 3.6% for a fourth straight month, and for wage growth to remain steady at 0.3% MoM (5.0% YoY).''
The minutes of the fed's June meeting will also be eyed. ''Persistent high CPI inflation and nascent signs of de-anchoring inflation expectations forced the Fed to amp the pace of rate tightening. The meeting minutes are likely to offer further colour around the Fed's more hawkish reaction function,'' the analysts at TD Securities said.
DXY daily chart
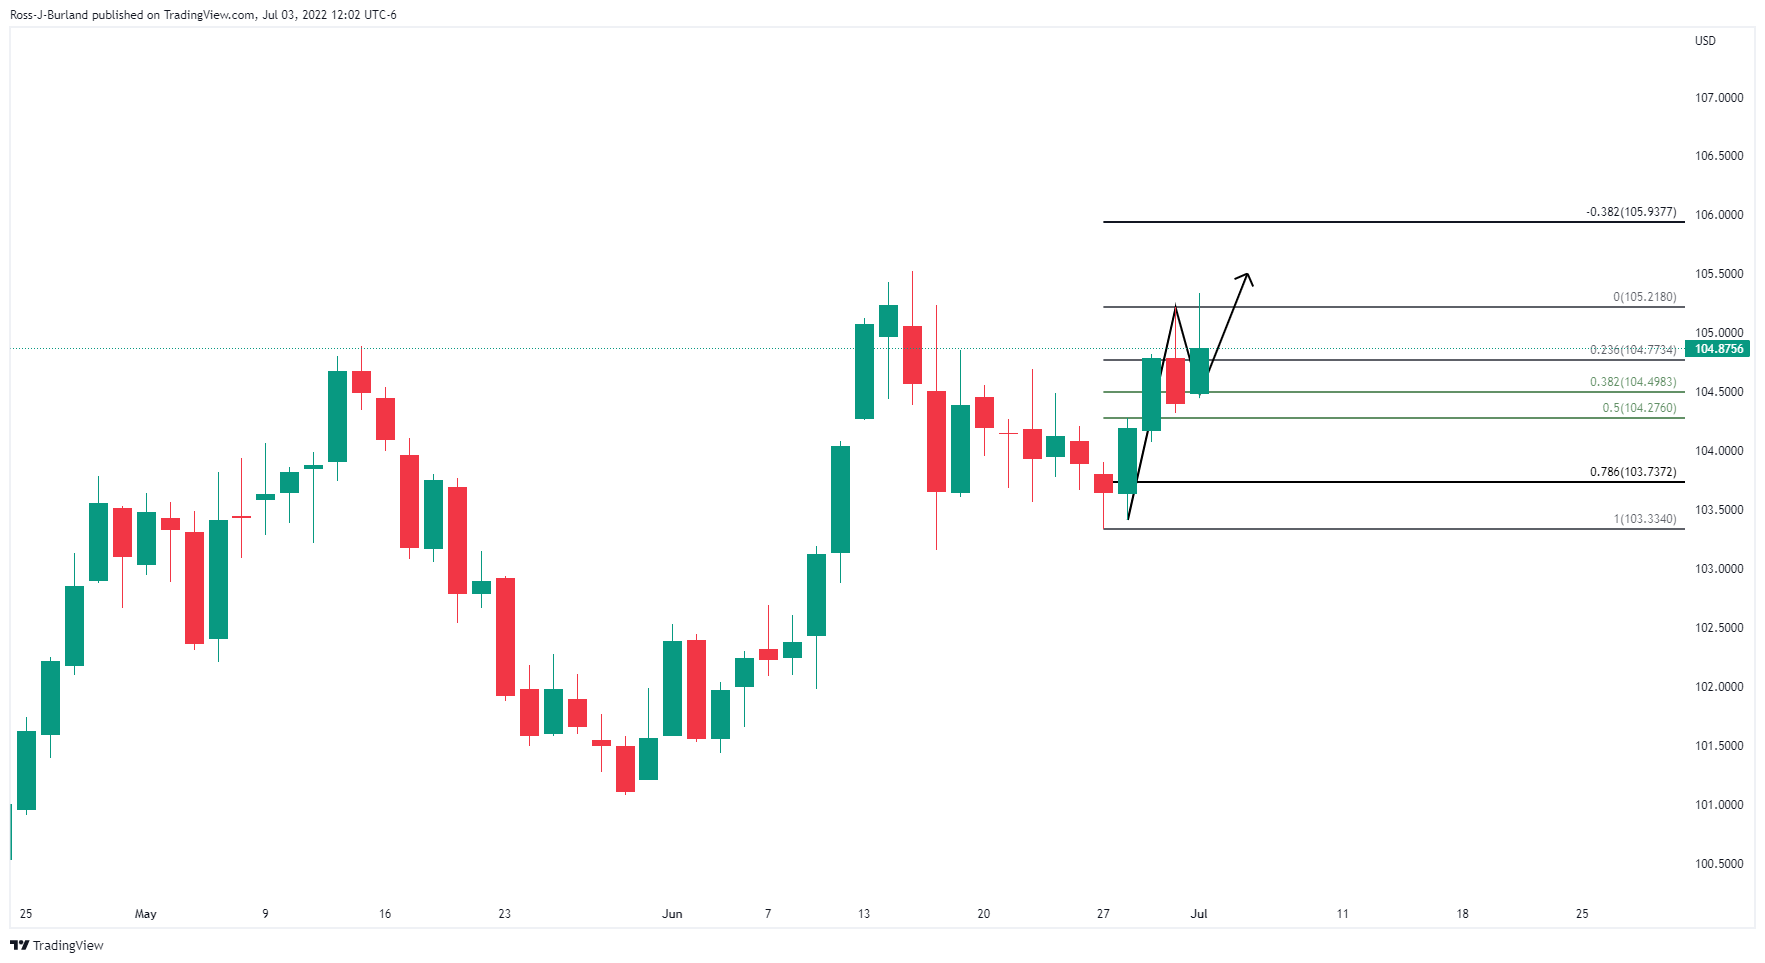
The bulls have made their move from key ratios along the Fobo scale and from near a 50% mean reversion. Eyes are on a move to test 105.50 for the weekend ahead for a daily extension towards bull cycle highs.
-
18:56
EUR/USD: A busy week ahead with Fed & ECB minutes as well as Nonfarm Payrolls
- EUR/USD will be vulnerable to critical events in the week ahead.
- US data will be watched closely as will the Fed and ECB minutes.
EUR/USD was down some 0.5% on Friday due to the pick-up in pessimism about the global economic outlook. The US dollar has found its feet yet again due to the demand for the safe-haven currency. The euro fell to a low of 1.0365 vs the greenback from a high close to the 1.05 area.
The potency of tighter monetary expectations in the face of higher in inflation is playing havoc on markets and supporting demand for US assets which has sent the benchmark 10-year US Treasury yields to one-month lows.
The Federal Reserve is expected to continue to hike rates in the face of soaring price pressures at the same time that investors are worrying over the economic outlook. Data on Friday did little to squash the concerns with US manufacturing activity slowing more than expected in June, with a measure of new orders contracting for the first time in two years.
Nevertheless, the US dollar index gained 0.36% against a basket of currencies to 105.12, albeit still trading shy of the 20-year high of 105.79 reached on June 15. This has crippled the euro, putting the focus back on the five-year low of $1.0349 printed on May 13 even though the European Central Bank is also expected to raise interest rates this month. This will be the first time in a decade, although economists are divided on the size of any hike.
The week ahead
The minutes of the ECB's June meeting will likely be eyed but analysts at TD Securities said they will be ''somewhat stale as we have since heard from many officials at the Sintra conference. That said, we will look for any indication of what is needed for an above 25bps hike in July, and how the risks of weaker growth could impact policy beyond that, given the further deterioration of growth prospects in the euro area.''
Instead, the major focus for the week ahead will lie in the US data once again. Nonfarm Payrolls is expected to show that Employment likely continued to advance firmly in June but at a more moderate pace after three consecutive job gains of around 400k in March-May, the analysts at TD Securities said. ''High-frequency data, including Homebase, still point to above-trend job creation. We also look for the UE rate to stay unchanged at 3.6% for a fourth straight month, and for wage growth to remain steady at 0.3% MoM (5.0% YoY).''
Fed minutes will also be eyed after the Fed's meeting where it surprised markets with a 75bps hike at the June meeting. ''Persistent high CPI inflation and nascent signs of de-anchoring inflation expectations forced the Fed to amp the pace of rate tightening. The meeting minutes are likely to offer further colour around the Fed's more hawkish reaction function,'' the analysts at TD Securities said.
-
18:15
AUD/USD Price Analysis: The bulls could be on the verge of a move ahead of RBA
- All eyes will be o the RBA this week as the Aussie will depend on it.
- AUD/USD is setting up for a move higher as per the current market structure.
AUD/USD is one to watch this week ahead in the countdown to the Reserve Bank of Australia. Governor Lowe made it clear that the Board will discuss either a 25bps or 50bps hike this week, so there is fuel for a move one way or the other in AUD depending on the outcome of that meeting.
This draws us to the current structure on the charts in AUD/USD and the M-formation on the daily time frame is compelling for a meanwhile bid in the run-up to the meeting and the RBA's statement, July 5. If it is not particularly hawkish, meanwhile mitigation of any price imbalance to the upside could be the site up for fresh daily lows.
AUD/USD daily chart
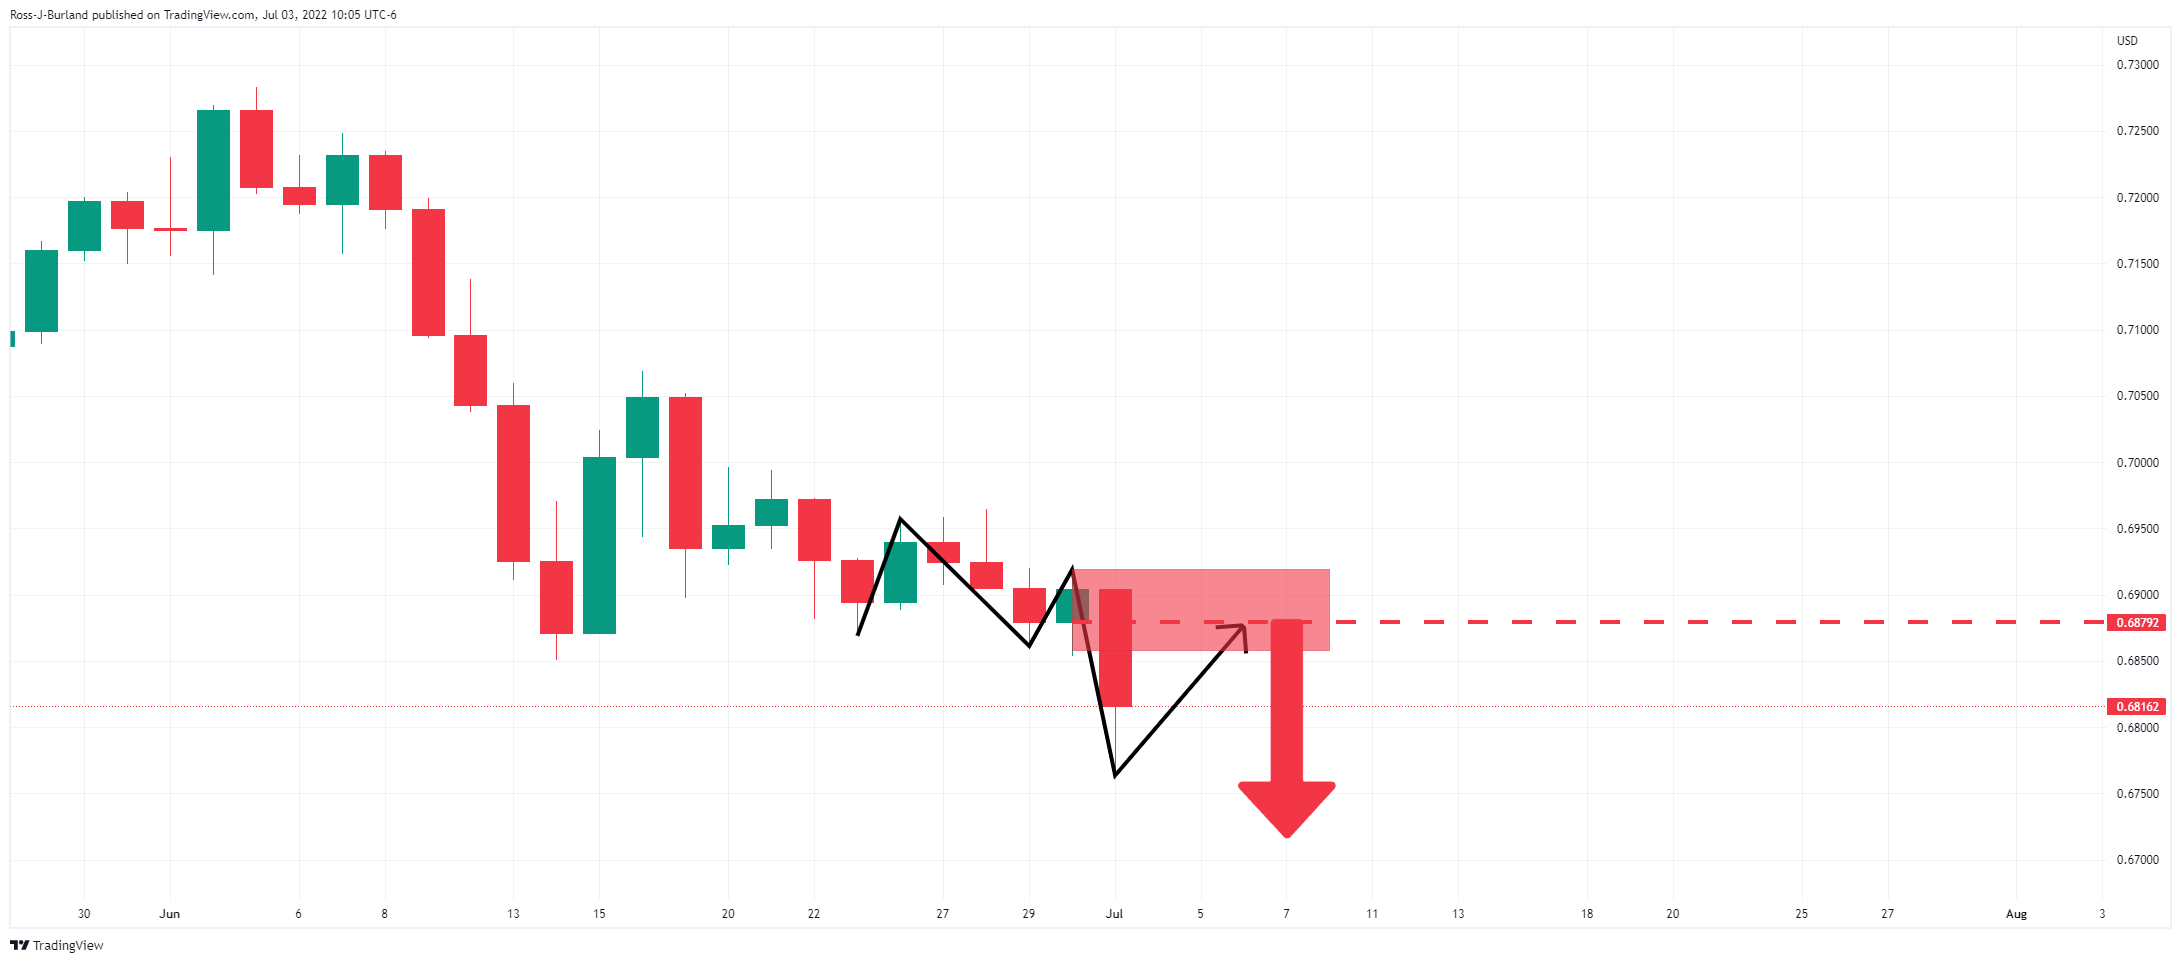
The 0.6880s are often regarded as a psychological area on the charts and the M-formation's neckline, or older block, is lining up there which could draw in the price in the coming sessions ahead of the RBA.
However, the price imbalance on the hourly time frame is an area that could be mitigated first of all:
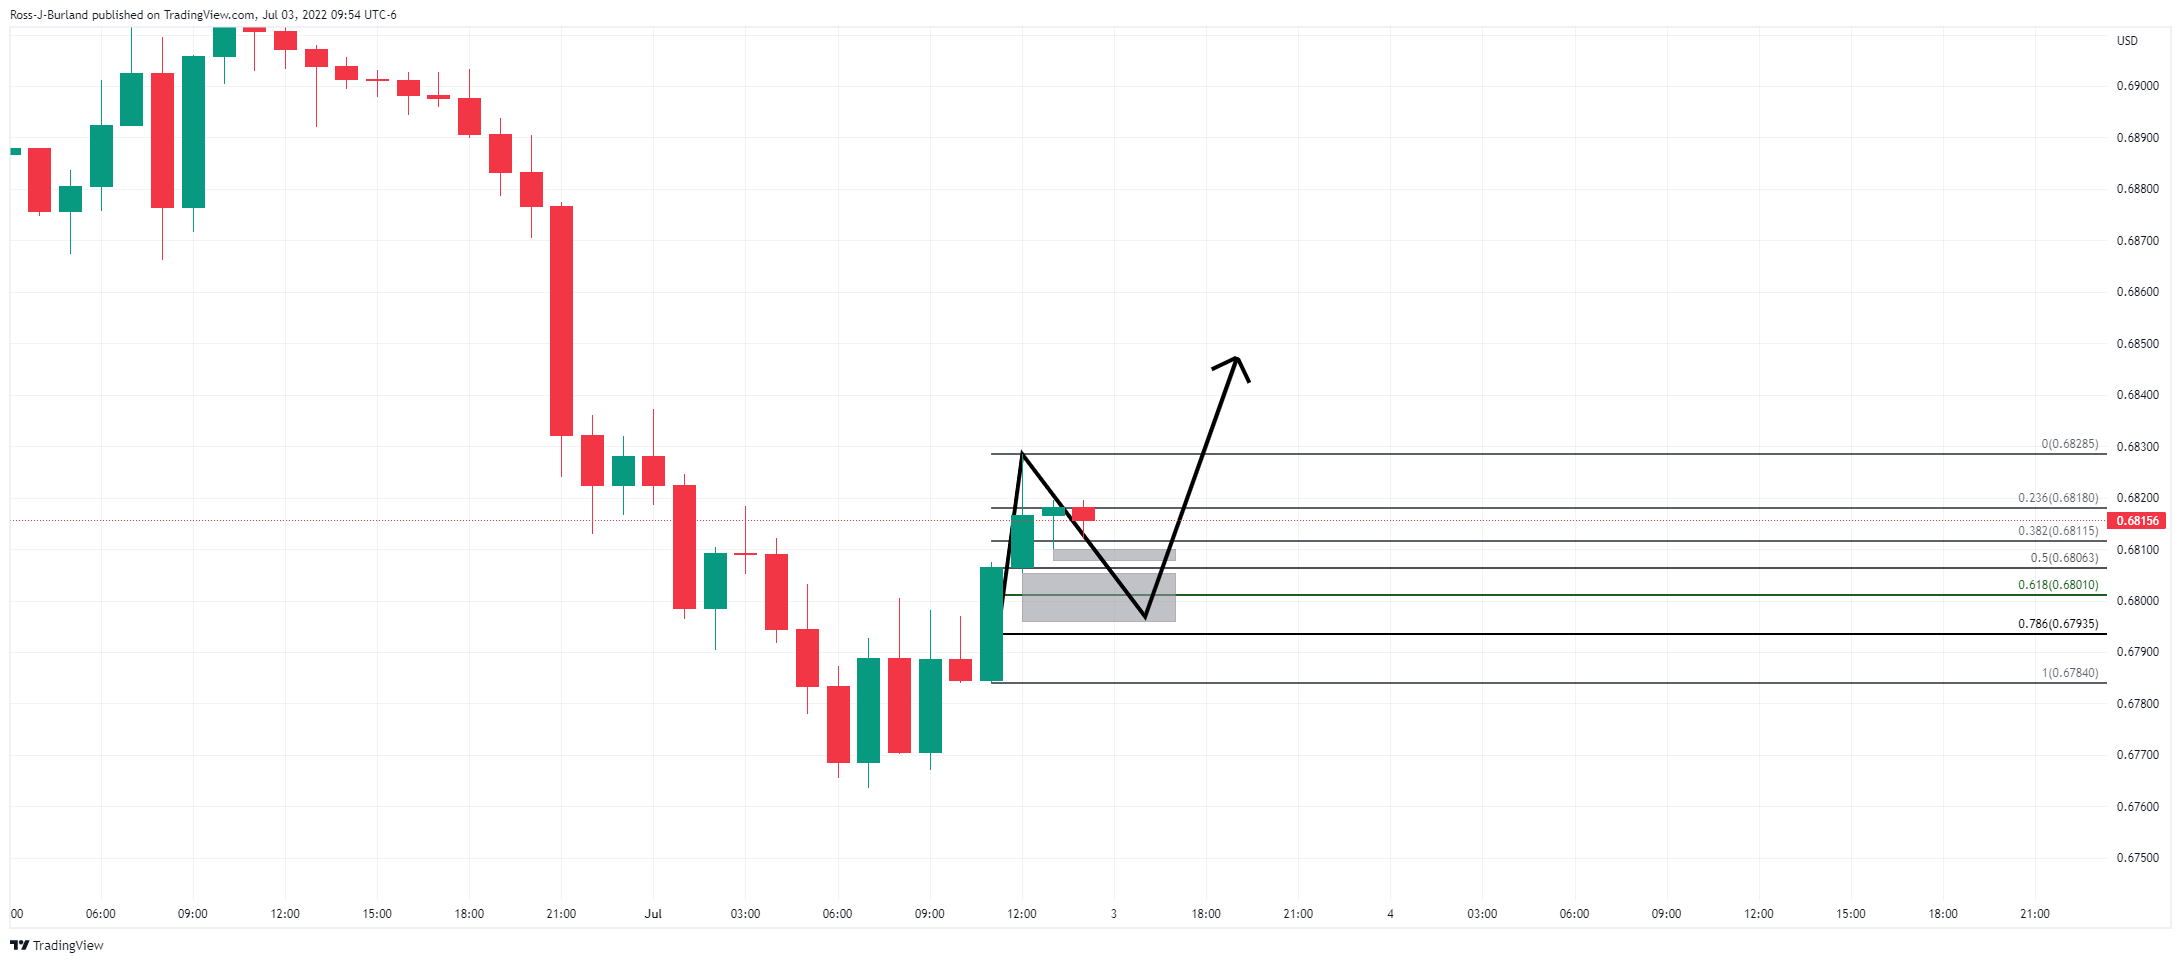
AUD/USD M15 chart
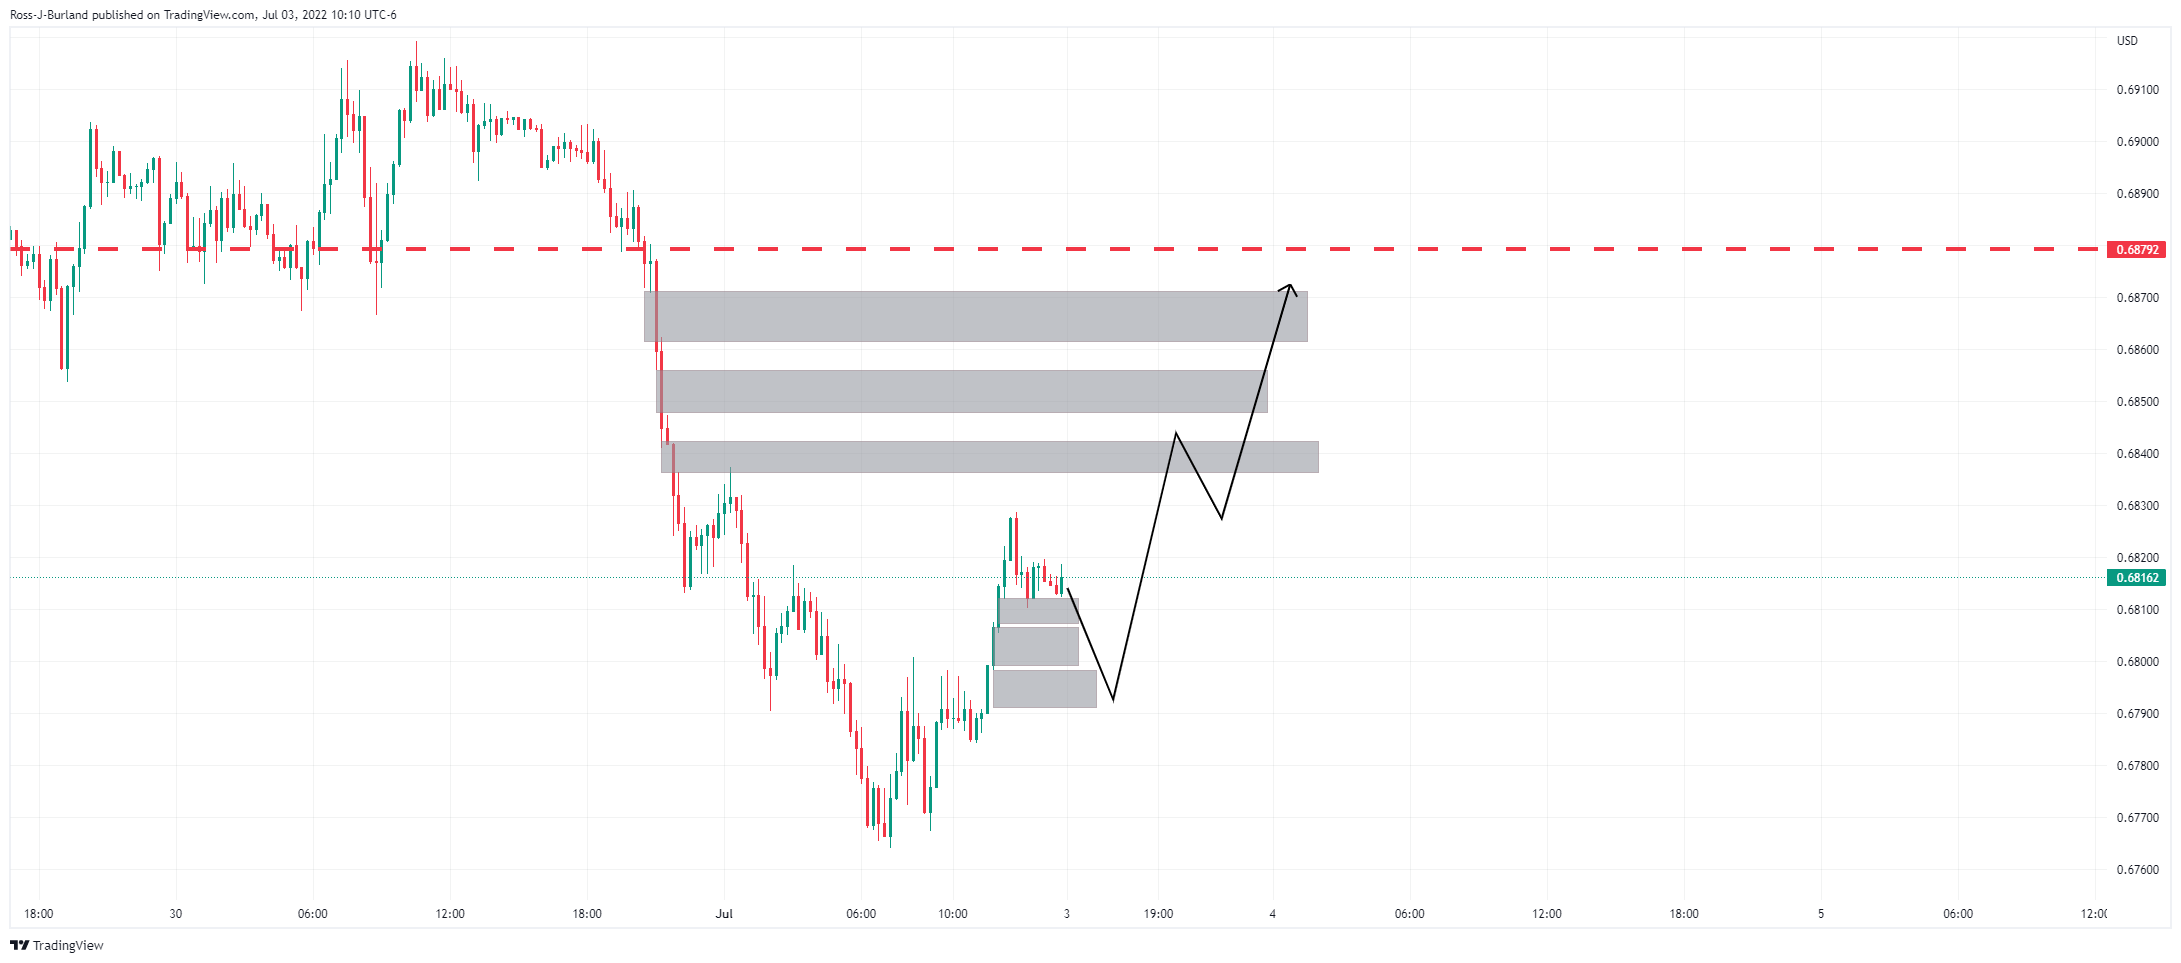
The price on the 15-min chart is also building up for a breakout one way or the other and given the nature of markets, the downside mitigation process could be perceived as the bias prior to the continuation move to the upside and imbalances along the way.
-
 Material posted here is solely for information purposes and reliance on this may lead to losses. Past performances are not a reliable indicator of future results. Please read our full disclaimer